Financial Education for Entrepreneurs: 6 Essential Strategies for 2026
Anúncios
The entrepreneurial journey is full of challenges and rewards, but one of the pillars of lasting success is, without a doubt, solid financial education. In 2026, with a constantly evolving economy and the growing digitalization of business, the ability to manage finances effectively becomes even more crucial. For entrepreneurs, the line between personal and business can be thin, and the lack of clear separation is one of the main reasons small and midsize businesses fail. This article was carefully crafted to offer a practical, strategic guide focused on 6 essential financial education strategies for entrepreneurs, with the goal of ensuring your business’s financial health and your personal peace of mind.
Anúncios
With technological advances and new market dynamics, financial tools and approaches are evolving too. Staying up to date and applying best practices is key not only to surviving but to thriving in the competitive environment of 2026. We’ll cover everything from the importance of a financial mindset to using technology to optimize management, always with an eye on the sustainability and growth of your business.
Get ready to dive into content that will transform your relationship with money, both personally and professionally. The strategies presented here are an invitation to take full control of your finances, make sharper decisions and build a solid financial future for you and your business. Let’s explore the path to exemplary financial management in 2026 together.
Anúncios
The Crucial Importance of Financial Education for Entrepreneurs in 2026
In an increasingly dynamic and unpredictable world, financial education for entrepreneurs is not just a differentiator but an absolute necessity. The year 2026 brings new trends, challenges and opportunities that demand sharp vision and impeccable financial control from business owners. The ability to understand and apply basic and advanced financial concepts is what separates success from failure.
Many entrepreneurs start their businesses with great passion and vision but underestimate the complexity of financial management. Mixing personal and business finances is a common and dangerous mistake. When company money gets mixed with household expenses, the health of both suffers. The business loses its ability to reinvest, cover operating costs and plan for the future, while the entrepreneur may find themselves in growing personal debt, directly affecting their quality of life and their ability to make rational business decisions.
In addition, the global economic landscape of 2026 demands unprecedented financial adaptability. Market fluctuations, technological innovations that require investment and pressure for sustainability and social responsibility all directly influence cash flow and profitability. An entrepreneur with solid financial education is better prepared to anticipate these shifts, mitigate risks and identify new growth opportunities.
Financial education allows entrepreneurs to:
- Make informed decisions: Based on data and analysis, not intuition or emotion.
- Manage cash flow: Essential for the survival and growth of any business.
- Plan investments: Whether in expansion, new equipment or marketing.
- Negotiate with suppliers and customers: With a clear understanding of costs and margins.
- Handle crises: By having reserves and contingency plans.
- Evaluate profitability: By understanding what really generates profit for the business.
So investing time and effort in financial education is investing in the future of your business and your own security. It’s the foundation on which a resilient, prosperous business is built. The strategies we’ll cover next are the path to strengthening that foundation.
Strategy 1: Set Your Owner’s Salary and Separate Personal and Business Accounts
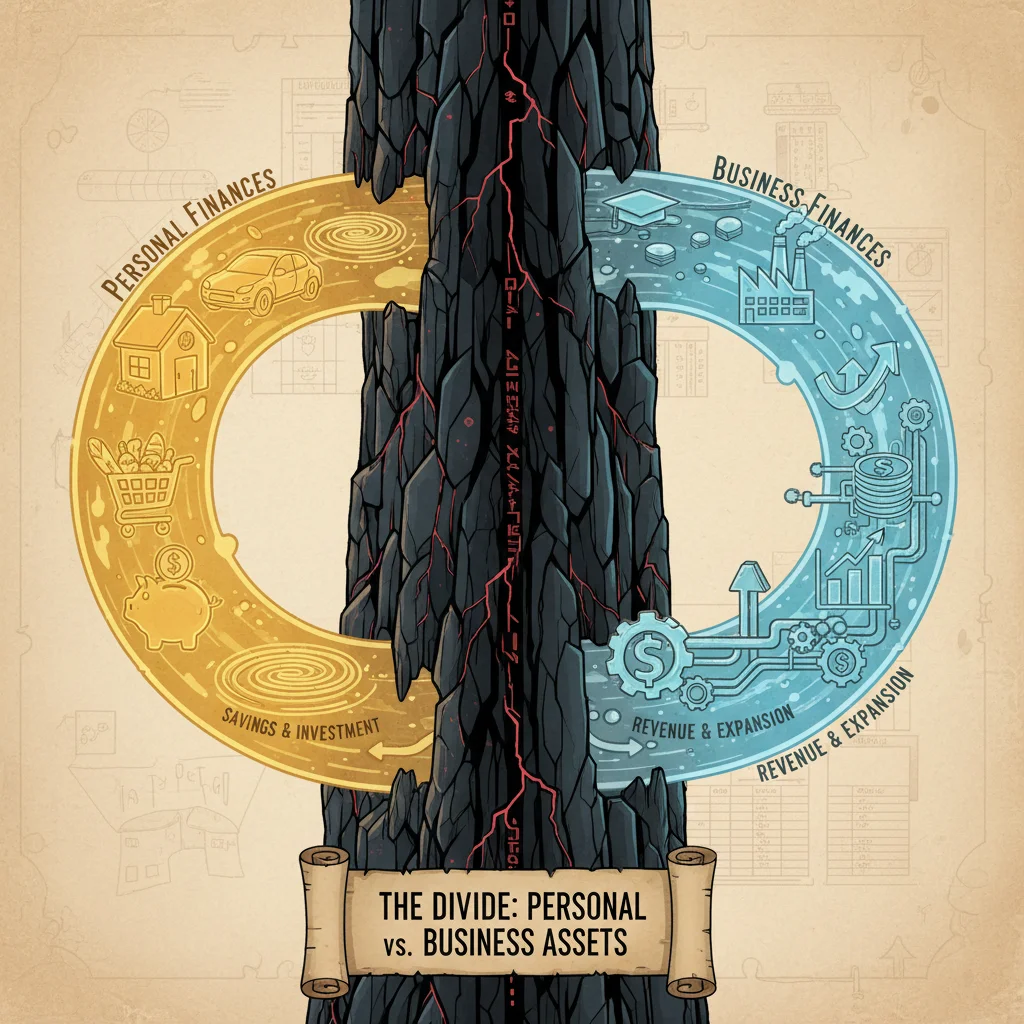
The first and most fundamental strategy for any entrepreneur is to establish a clear, unquestionable separation between personal and business finances. In 2026, with how easy it is to open digital accounts and use management tools, there’s no excuse for mixing the two. This practice not only professionalizes your management but also protects your personal assets and ensures your company’s financial health.
What Is an Owner’s Salary?
An owner’s salary is the compensation a business owner receives for their work in the company. Unlike an employee’s wages or a distribution of profits, it’s a fixed amount that should be set realistically, considering the entrepreneur’s personal needs and the company’s ability to pay. It’s your ‘salary’ as the manager of the business.
How to Set an Appropriate Owner’s Salary
- Analyze your personal needs: List all your monthly expenses (housing, food, transportation, entertainment, etc.). This amount will be the baseline for your owner’s salary.
- Evaluate the company’s capacity: Your owner’s salary can’t compromise the business’s cash flow. It should be an amount the company can pay consistently without running into trouble.
- Research the market: How much would a professional in your role earn on the job market? This can serve as a benchmark.
- Start small if necessary: If the company is just getting started, begin with a smaller owner’s salary and increase it gradually as the business grows and becomes more profitable.
Separating Your Accounts
Once your owner’s salary is set, the next step is physically separating your bank accounts. Have a checking account just for the business and another for your personal finances. It sounds obvious, but many entrepreneurs still fall short here.
Benefits of Separate Accounts:
- Financial Clarity: You’ll know exactly how much money the business has and how much is yours for personal use.
- Spending Control: It makes it easier to track expenses and revenue on both sides.
- Accountability: It simplifies the company’s bookkeeping, which is essential for tax filing and audits.
- Legal Protection: If the business runs into financial trouble, your personal assets will be better protected.
- Decision-Making: It allows a more accurate analysis of business performance, avoiding decisions based on a distorted view of cash.
In 2026, digital banks and integrated financial management platforms (which we’ll cover later) make this separation even easier and more efficient. Set up automatic transfers of your owner’s salary from the business account to your personal account on a fixed date, just like a paycheck. This builds discipline and reinforces the mindset that the company’s money isn’t yours until it’s formally transferred as salary or a profit distribution.
Strategy 2: Create a Detailed Budget for Your Business and Your Personal Life
After separating your accounts and setting your owner’s salary, the next crucial step in financial education for entrepreneurs in 2026 is creating detailed budgets. Having a budget isn’t just about controlling spending; it’s a strategic tool for planning, monitoring and adjusting your finances, ensuring resources are allocated efficiently in both your business and personal life.
Business Budget: Your Company’s Financial Map
A business budget is your company’s financial plan for a specific period (usually annual, with monthly or quarterly reviews). It projects expected revenue, expenses, investments and profits. In 2026, with market volatility, flexibility and the ability to revise constantly are even more important.
Components of an Effective Business Budget:
- Revenue Forecast: Estimate your sales and other revenue sources based on historical data, 2026 market trends and growth projections.
- Fixed Costs: Expenses that don’t vary with sales volume (rent, fixed salaries, insurance, management software, etc.).
- Variable Costs: Expenses that rise or fall with production or sales volume (raw materials, sales commissions, shipping, etc.).
- Operating Expenses: Costs needed to run the business that aren’t directly tied to production (marketing, administrative expenses, consulting).
- Investments: Capital set aside for improvements, expansion, asset or technology purchases (new equipment, product development, team training).
- Taxes and Payroll Costs: Plan for tax payments and payroll contributions.
Use spreadsheets (Excel, Google Sheets) or financial management software with budgeting features. Regularly compare budgeted versus actual figures, identifying variances and taking proactive corrective action.
Personal Budget: The Foundation of Your Stability
Just like your business, your personal life needs a budget too. Remember, the goal is for your owner’s salary to cover your personal expenses and allow you to build your own emergency fund and invest in your future.
Elements of an Effective Personal Budget:
- Net Income: Your owner’s salary and any other sources of personal income.
- Fixed Expenses: Rent/mortgage, utilities (water, electricity, internet), monthly fees (school, gym), loan payments.
- Variable Expenses: Food, transportation, entertainment, clothing, health.
- Savings and Investments: Set goals for your personal emergency fund and long-term investments.
- Debt: Plan how to pay off existing debt.
The 50/30/20 rule (50% for needs, 30% for wants, 20% for savings/debt repayment) can be a good starting point, but adapt it to your reality. What matters is having control and awareness of where your money is going. In 2026, personal finance apps are excellent allies for this task.
Creating detailed budgets, for both your business and your personal life, is a pillar of financial education for entrepreneurs. It provides visibility, control and the ability to make strategic decisions that will drive growth and sustainability in 2026 and beyond.
Strategy 3: Keep Rigorous Cash Flow Records and Future Projections
Cash flow is the heart of any business. For entrepreneurs in 2026, maintaining rigorous control and making future projections is more than good practice; it’s a matter of survival and sustainable growth. Strategy 3 of financial education for entrepreneurs focuses on actively managing the money coming in and going out of your business.
What Is Cash Flow?
Cash flow is the record of all money coming in (revenue) and going out (expenses) of your business over a given period. It shows the real availability of your company’s capital, meaning how much money you have on hand or in the bank at any given moment. Healthy cash flow means the company has the resources to meet its obligations and invest.
The Importance of Rigorous Control
Daily or weekly cash flow tracking allows you to:
- Identify problems quickly: If outflows are exceeding inflows, you can act before the situation gets worse.
- Optimize working capital: Understand how much money you need on hand to operate without interruptions.
- Negotiate terms: Based on your ability to pay, you can negotiate better terms with suppliers and customers.
- Avoid unnecessary debt: With clarity about your liquidity, you avoid turning to expensive loans.
- Assess financial health: Cash flow is a vital indicator of your business’s viability.
Cash Flow Projections: Looking Ahead
Besides recording the past and present, it’s crucial to project your cash flow into the future. A cash flow projection estimates expected inflows and outflows for the coming months or even a year. In 2026, given the speed of change, short- and medium-term projections are indispensable.
How to Make Effective Projections:
- Use historical data: Use your past records as a starting point.
- Consider market trends: Analyze economic forecasts for 2026, seasonality in your industry and the impact of new technologies or regulations.
- Include future events: New product launches, marketing campaigns, equipment purchases, new hires.
- Optimistic and pessimistic scenarios: Prepare projections for different scenarios (best case, worst case and most likely) so you’re ready for anything.
Financial management tools (ERP, accounting software) are powerful allies for automating cash flow tracking and making projections easier. In 2026, many of these tools already incorporate artificial intelligence to predict trends and warn of potential financial bottlenecks.
Mastering cash flow and its projections is an essential part of financial education for entrepreneurs. It provides the visibility needed to make strategic decisions, anticipate problems and ensure your business always has the capital it needs to operate and grow.
Strategy 4: Build Emergency Funds (Business and Personal)
Entrepreneurial life is full of uncertainty. Economic downturns, equipment failures, unexpected drops in sales or even personal health problems can destabilize both the business and the entrepreneur’s life. That’s why Strategy 4 of financial education for entrepreneurs is building emergency funds, for both the company and the individual. In 2026, financial resilience is an invaluable asset.
Business Emergency Fund: Your Company’s Safety Cushion
A business emergency fund is a pool of capital the company keeps separate to cover unexpected expenses or periods of low revenue. It works as a ‘cushion’ that absorbs financial shocks, keeping the business from having to turn to expensive loans or, in extreme cases, close its doors.
How to Calculate and Build Your Business Reserve:
- List your monthly fixed expenses: Include rent, salaries, utilities, insurance, essential software and fixed taxes.
- Set the coverage period: It’s generally recommended to have 3 to 12 months of fixed expenses covered by the reserve. For more volatile businesses or high-risk sectors, 6 to 12 months is ideal.
- Start saving: Set aside a percentage of monthly profits for this reserve. Treat it as a fixed expense, a priority.
- Where to keep it: The reserve should be held in highly liquid, low-risk options, such as high-yield savings accounts, money market funds or Treasury bills, so the money is available when needed.
Having a robust business reserve in 2026 lets you make more rational decisions during crises, without the desperation of cutting essential expenses or laying off valuable employees. It’s an investment in your business’s stability and longevity.
Personal Emergency Fund: Your Individual Financial Security
Just like your business, you as an individual also need an emergency fund. This fund covers your personal expenses in case of the unexpected, such as a medical emergency, an urgent home repair or, in the entrepreneurial context, a period when your owner’s salary has to be temporarily reduced to support the business.
How to Calculate and Build Your Personal Reserve:
- List your monthly personal expenses: The same ones you used to set your owner’s salary.
- Set the coverage period: 6 to 12 months of personal expenses is recommended. For entrepreneurs, it’s prudent to aim for 12 months, given the greater income instability.
- Create a savings plan: Automate monthly transfers from your owner’s salary to your emergency fund account.
- Where to keep it: Just like the business reserve, use highly liquid, low-risk options.
A personal emergency fund gives you peace of mind and keeps you from pulling money out of the business to cover personal emergencies, a common and harmful mistake. It provides the security you need to focus on your business without constant worry about personal financial surprises.
Both reserves are pillars of financial education for entrepreneurs. They provide the security and flexibility needed to face the challenges of 2026, allowing you and your business not just to survive but to thrive, even in the face of unexpected adversity.
Strategy 5: Invest in Financial Knowledge and Management Tools
In 2026, technology and access to information have transformed the way businesses are run. For entrepreneurs, Strategy 5 of financial education for entrepreneurs is clear: continuously invest in financial knowledge and adopt the right management tools. This isn’t an expense but an investment that will deliver significant returns in efficiency, control and decision-making.
Invest in Financial Knowledge
The world of finance is constantly evolving. New regulations, financial products, investment strategies and business models emerge all the time. Staying up to date is essential. Financial knowledge isn’t just about doing the math; it involves understanding economics, taxation, investments, market analysis and strategic planning.
Ways to Invest in Knowledge:
- Courses and Workshops: There are countless online and in-person courses on finance for entrepreneurs, accounting, cash flow, pricing and investing. Look for reputable institutions and content updated for 2026.
- Books and E-books: The literature on finance is vast. Choose authors and topics relevant to your stage and type of business.
- Specialized Blogs and Podcasts: Many experts share valuable content for free or by subscription, keeping you up to date on the latest trends and analysis.
- Financial Consulting: For more complex issues or an outside expert perspective, hiring a financial advisor can be a very valuable investment.
- Networking: Sharing experiences with other entrepreneurs and finance professionals can generate important insights and practical lessons.
Learning about business and personal finance boosts your confidence, improves your negotiating skills and helps you spot opportunities and risks that would otherwise go unnoticed. It’s empowerment through information.
Adopt Financial Management Tools
The digital age offers a wide range of tools that can automate, simplify and optimize your business’s financial management. In 2026, using these tools is no longer a luxury but a necessity to stay competitive.
Types of Essential Tools:
- Financial Management Software (ERP): Integrated systems that handle invoicing, accounts payable and receivable, cash flow, inventory, accounting and often payroll. Examples include QuickBooks, Xero, FreshBooks and Zoho Books.
- Personal Finance Apps: To manage your personal finances efficiently, such as YNAB, Monarch Money and Rocket Money.
- Bank Reconciliation Platforms: They automate the comparison between bank statements and internal records, saving time and reducing errors.
- Business Intelligence (BI) Tools: To analyze complex financial data and generate visual reports that support strategic decision-making.
- Digital Banks and Fintechs: They offer business accounts with low or zero fees, integration with management software and innovative features.
By automating repetitive tasks and accessing real-time data, you free up time to focus on growing your business and on strategic decisions. The ideal tool depends on the size and complexity of your business, but what matters is taking the first step toward digitizing your financial management.
Investing in knowledge and tools is one of the most effective strategies of financial education for entrepreneurs in 2026. It empowers you to maintain robust financial control, make smarter decisions and position your business for long-term success.
Strategy 6: Plan Your Retirement and Business Succession
The last, but by no means least, strategy of financial education for entrepreneurs in 2026 is thinking about the long-term future: your retirement and your business’s succession. Many entrepreneurs get so immersed in day-to-day operations that they forget to plan what will happen when they decide to slow down or retire, or even what will happen to the company in their absence. This planning is crucial to ensure your personal financial security and the continuity of your business’s legacy.
Retirement Planning for Entrepreneurs
Unlike a W-2 employee, who may have access to an employer-sponsored retirement plan, an entrepreneur needs to be proactive about retirement planning. Relying on Social Security alone may not be enough to maintain the lifestyle you want.
Steps for Effective Retirement Planning:
- Define your goals: What lifestyle do you want in retirement? At what age do you plan to stop working?
- Calculate how much you’ll need: Estimate your future expenses and how much capital will be needed to cover them.
- Invest for the long term: In addition to Social Security, explore retirement accounts (such as an IRA, SEP IRA or Solo 401(k)), long-term investment funds, stocks and real estate. Diversification is key.
- Review regularly: Your retirement plan should be reviewed annually, adjusting it as your needs change and the financial markets evolve.
Separating personal and business finances (Strategy 1) is essential here, since it lets you contribute to your retirement without compromising the company’s cash. Your owner’s salary should be enough to cover your expenses and let you invest in your personal future.
Business Succession Planning: Ensuring Continuity
Succession planning is the process of identifying and developing future leaders who can take over key positions in the company when the current manager (you) steps away. This ensures continuity of operations, protects the value of the business and minimizes risks in case of the unexpected.
Elements of a Robust Succession Plan:
- Identify potential successors: People inside or outside the company with the necessary potential and skills.
- Develop talent: Offer training, mentoring and development opportunities to prepare these individuals.
- Document processes and knowledge: Create manuals and flowcharts, and capture tacit knowledge so the transition is smooth.
- Set a timeline: Establish deadlines for the transition, whether planned (retirement) or unexpected.
- Consider exit options: Selling the company, passing it on to heirs, a merger, etc. Having a clear plan increases your business’s market value.
- Legal and Tax Considerations: Consult attorneys and accountants to ensure the plan complies with the law and optimizes your tax burden.
A well-crafted succession plan not only protects your assets but also the legacy you’ve built. It demonstrates professionalism and long-term vision, increasing the confidence of investors, employees and customers in the company’s future. In 2026, with the growing value placed on corporate governance, this planning is a competitive advantage.
Both plans are a testament to your maturity as an entrepreneur and your understanding of financial education for entrepreneurs as a whole. They ensure that your hard work today translates into security and prosperity for you and your business in the future.
Conclusion: Financial Education as a Pillar of Entrepreneurship in 2026
We’ve reached the end of our journey through the 6 essential strategies of financial education for entrepreneurs in 2026. It’s clear that, more than ever, financial management isn’t just an operational task but a fundamental strategic skill for the survival and growth of any business. In an increasingly volatile and competitive global landscape, being a financially educated entrepreneur means resilience, innovation and long-term success.
To recap, the strategies covered are interconnected and form a robust financial management ecosystem:
- Setting an Owner’s Salary and Separating Accounts: The foundation for transparent, professional management, protecting both personal and business assets.
- Creating Detailed Budgets (Business and Personal): Essential tools to plan, monitor and control revenue and expenses, ensuring efficient allocation of resources.
- Maintaining Rigorous Cash Flow and Future Projections: The heart of the business, offering real-time visibility and the ability to anticipate scenarios and make proactive decisions.
- Building Emergency Funds (Business and Personal): The ‘safety cushions’ that provide stability and let you face the unexpected without compromising financial health.
- Investing in Knowledge and Financial Management Tools: The lever for sharpening skills, optimizing processes and making smarter decisions, boosting efficiency and competitiveness.
- Retirement and Business Succession Planning: The long-term vision that ensures the entrepreneur’s financial security and the continuity of the business’s legacy.
Each of these strategies, when applied with discipline and consistency, helps build a solid business capable of navigating the challenges and seizing the opportunities that 2026 and the following years will bring. Remember, financial education is an ongoing process. The market changes, technology evolves and so do your needs as an entrepreneur. Stay curious, keep learning and keep adapting your practices.
Your business’s success isn’t measured by revenue alone but by its ability to create value sustainably, delivering not only profits but also peace of mind and security for you and everyone involved. Invest in your financial education for entrepreneurs today and reap the rewards of a prosperous, successful future.
May this guide serve as a starting point for you to revolutionize your business’s financial management and reach new levels of success in 2026!