Family Financial Planning: How to Organize Your Finances
Anúncios
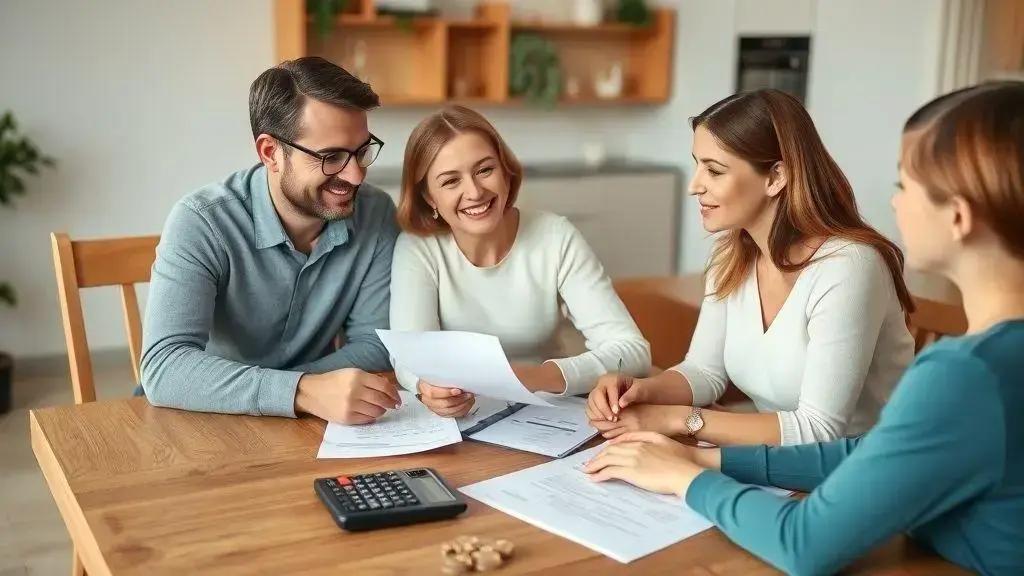
Family financial planning is essential for financial stability: it helps you avoid common mistakes, set clear goals and put everyday money-saving habits into practice.
Smart family financial planning can transform the way you and your family handle money. Have you ever stopped to think about how it can affect your quality of life and your household’s financial security? In this article, we’ll explore the best practices for organizing your resources and reaching your goals.
Anúncios
What is family financial planning?
Smart family financial planning is an essential practice for ensuring the financial well-being of everyone in a household. It involves organizing income and expenses with the goal of achieving healthy finances.
This organization lets the family know exactly where its money is going. With proper planning, you can avoid surprises and make sure each member’s needs are met. Planning is also key to reaching short-, medium- and long-term goals.
Anúncios
Components of financial planning
There are a few key elements to consider when putting together a financial plan. Let’s highlight the following:
- Budget: A tool that helps you track and control day-to-day expenses.
- Financial goals: Setting clear objectives, such as saving for a trip or buying a home.
- Emergency fund: Important for avoiding debt when the unexpected happens.
- Investments: Putting your money to work for you to secure a more comfortable future.
Keeping mindful spending habits is also a vital part of family financial planning. When you always pay attention to what you spend, it’s easier to adjust your budget and prioritize what really matters.
Other factors, like financial literacy, also contribute to successful planning. Families who make an effort to learn how to manage money well tend to be more successful with their finances. That’s why open conversations about money are necessary and should be part of everyday family life.
In short, family financial planning is a fundamental pillar for making sure everyone in the family has a more secure financial future. The decisions you make today will shape everyone’s quality of life tomorrow.
Why a monthly budget matters
One of the most essential parts of family financial planning is the monthly budget. It serves as a guide, giving families clarity about their income and spending and helping them reach their financial goals.
Smart budget planning gives you a clear view of where your money is going and where you can save. This makes it easier to spot unnecessary expenses and adjust your spending habits.
Benefits of a monthly budget
When you create a budget, you’ll notice many advantages:
- Financial control: With a budget, you keep a close eye on your spending and avoid surprises at the end of the month.
- Setting priorities: It helps you identify which expenses are essential and which can be cut.
- Investment planning: It makes it easier to build an emergency fund or invest for the future.
- Less stress: Having a clear budget reduces anxiety about money.
Many people underestimate the impact a monthly budget can have on their finances. But it’s essential for building a stronger financial future. When well structured, a monthly budget becomes a powerful tool that helps families achieve their goals and dreams.
It’s also important to review and adjust your budget regularly, since financial circumstances and expenses can change over time. A flexible budget lets you adapt to new situations without compromising your financial goals.
How to set family financial goals
Setting family financial goals is a crucial step in family financial planning. Clear goals let family members work together toward shared objectives, creating a sense of unity and purpose.
For these goals to be effective, they should be specific, measurable, achievable, relevant and time-bound. That way, the family can track its progress and make adjustments as needed. A well-defined goal becomes a project to carry out, not just a vague wish.
Types of financial goals
Financial goals can be grouped into three main categories:
- Short-term goals: Goals you can reach within a year, such as saving for a vacation.
- Medium-term goals: These usually take one to five years to reach, such as buying a new car.
- Long-term goals: These require more extensive planning, such as saving for retirement or your children’s education.
An important step in setting these goals is involving every family member in the conversation. This makes sure everyone knows the goals and is motivated to reach them. Working together also helps strengthen communication and collaboration within the family.
It’s also a good idea to review these goals periodically. Circumstances can change, and goals may need to be adjusted. What matters is that the family stays committed to its financial health and to making everyone’s dreams come true.
Tips for saving money every day
Saving money day to day is an essential skill in family financial planning. With a few small changes in habits, you can make a big difference in your monthly budget.
One important tip is to always shop around before you buy. Comparing prices at different stores can lead to significant savings. It’s also smart to keep an eye out for sales and coupons you can use.
Practical everyday tips
Here are some useful tips to help you save every day:
- Bring a shopping list: This habit prevents impulse buys and ensures you only buy what you need.
- Cook at home: Cooking at home isn’t just healthier — it’s also much cheaper than eating out.
- Use natural light: During the day, keep the lights off and use natural light whenever possible to save on your electric bill.
- Skip packaged drinks: Choosing filtered water or homemade tea is healthier and cheaper.
Another way to save is to review your subscriptions and recurring services. We often pay for services we don’t use. Canceling or renegotiating them can add up to significant savings.
Finally, get the whole family involved. Creating an environment where everyone is motivated to save can transform the way you handle money together. It turns saving into a fun, rewarding group activity.
Common financial planning mistakes to avoid
When working on your family financial planning, there are some common mistakes that can jeopardize your family’s financial success. Avoiding them is key to reaching your goals effectively.
The first mistake many people make is not having a clear budget plan. Without tracking income and expenses, it’s easy to lose sight of how much you spend. And a lack of discipline in sticking to the budget is another problem that can lead to debt.
Frequent financial planning mistakes
Below are some of the most common mistakes to avoid:
- Not setting priorities: It’s important to decide which expenses are essential and which can be reduced or eliminated.
- Ignoring the emergency fund: Not having money set aside for emergencies can cause major financial problems when the unexpected happens.
- Underestimating future expenses: Always account for expenses that may come up, such as car maintenance or education costs.
- Lack of communication: Ignoring the importance of discussing finances as a family can lead to misunderstandings and a lack of commitment.
Another common mistake is setting financial goals that are too ambitious without a clear plan for reaching them. It’s crucial that goals are realistic and broken down into smaller steps. This makes progress easier and keeps family members motivated.
Finally, it’s essential to remember that financial planning should be a dynamic process. Reviewing and adjusting your plan regularly is key, because financial circumstances change over time. Being open to change can make all the difference in your family’s financial health.
Smart family financial planning is a vital tool that helps families manage their finances effectively. By avoiding common mistakes, setting clear goals and saving day to day, you can achieve real financial stability. Open communication among family members is also essential to make sure everyone is aligned with your financial goals. By reviewing your financial plan regularly, every family can adapt to change and improve its financial health, building a more secure and productive future.
FAQ – Frequently asked questions about family financial planning
Why is family financial planning important?
Family financial planning is essential for organizing your finances, reaching your goals and ensuring financial stability for every member of the family.
What are the main financial planning mistakes to avoid?
The most common mistakes include not having a set budget, ignoring your emergency fund and not reviewing your financial goals regularly.
How can I save money every day?
Practical tips include making shopping lists, cooking at home and reviewing fixed costs, such as subscriptions, to make sure you’re not paying for services you don’t need.
How do I set effective financial goals?
Set goals that are specific, measurable, achievable, relevant and time-bound. Involve every family member and review your goals whenever necessary.